Cognitive biases
Loss aversion: why a loss weighs more than a gain
An evening with friends. Lisa takes out a coin and says: “Tails, you give me €10. Heads, I give you €10.” The odds are exactly fifty-fifty and the stakes are equal. The game is fair. And still, many people want to say no. Many would agree only if Lisa promised more than €10 for heads.
This is loss aversion: when we decide, a possible loss weighs more than a gain of the same size. So we often choose “lose nothing” over “gain more.” We accept a risk when the possible gain is clearly bigger than the possible loss.
Below, we look at what research has shown, how strong the effect turns out to be, and where it helps and where it gets in the way. In the middle of the article you will play a coin toss with Lisa and see how much a loss weighs for you personally.
Contents
In short: how loss aversion works
What loss aversion is
The idea was described by the psychologists Daniel Kahneman and Amos Tversky in a 1979 paper, which became the foundation of a whole theory of decision-making. The main idea is simple. When a person chooses, they think not about how much they will have in total but about what they will gain or lose compared with what they have now. And we judge losses more strictly than gains. Losing €10 and finding €10 are not the same thing for a decision.
How much more strictly? Scientists describe it with a single number: how many times more a loss weighs than a gain of the same size. If the number is 1, losses and gains weigh the same. If it is 2, a loss weighs twice as much.
A large review from 2024 collected hundreds of such estimates from 150 papers. On average it came out at about 2: a loss weighed roughly twice as much as a gain. But another review from the same year took only tasks involving risk, like the coin toss, and got a noticeably lower figure, about 1.3. There is little suitable data there, so the number is imprecise. The takeaway: the tilt toward losses exists, but its size depends on the task and differs a lot from person to person.
There are disputes, too. Some researchers believe that the data do not show that losses are, in general, stronger than gains. Others tested this on five groups of participants, more than 17,000 people in all: the effect showed up in people with any level of experience and knowledge, though it was weaker in experienced ones. The dispute is not over. But taken together, the data suggest that loss aversion exists. It is not a fixed amount but a tendency, stronger in some conditions and weaker in others.
Try it yourself: Lisa’s coin
It takes a minute. Here is what will happen.
Step 1. Lisa offers a fair game: tails, you give her €10; heads, she gives you €10. You decide whether to play.
Step 2. Lisa is ready to raise the prize. Tails, you still give €10, but for heads you get more. You move the slider and find the smallest win at which you would agree to play. The scales on the screen show right away what lies on each pan.
Step 3. At the end we show how many times more a loss weighs for you than a gain, and compare it with what scientists found.
Why is the game built this way? With €10 against €10 and even odds, the game is exactly fair: played many times, it averages out to zero. So whatever you ask for above €10 is your personal “premium” for the possible loss. You do not need a second group of players: the tilt shows up in a single person. True, part of the premium may be simply a dislike of risk, not only of losses. Scientists separate the two in more careful ways than a game can. The slider starts empty so that it does not suggest any number to you.
What usually happens. Many people turn down the fair game and agree when the win is more than €10. According to the reviews, a loss weighs on average about 1.3 to 2 times as much as a gain. In our game that would mean asking for about €13–20 for the risk of giving up €10. This is a rough conversion: scientists calculate the number in a more complicated way than we do in the game.
When it is not a mistake. If €10 is serious money for you, caution is reasonable: no win can balance a loss you cannot afford. You may also say no for other reasons: you don’t want to take money from a friend, or you simply don’t like betting on money. That is not loss aversion. It becomes a mistake when the loss is small and affordable, and you still turn down a game that is in your favor.
Why a loss weighs more
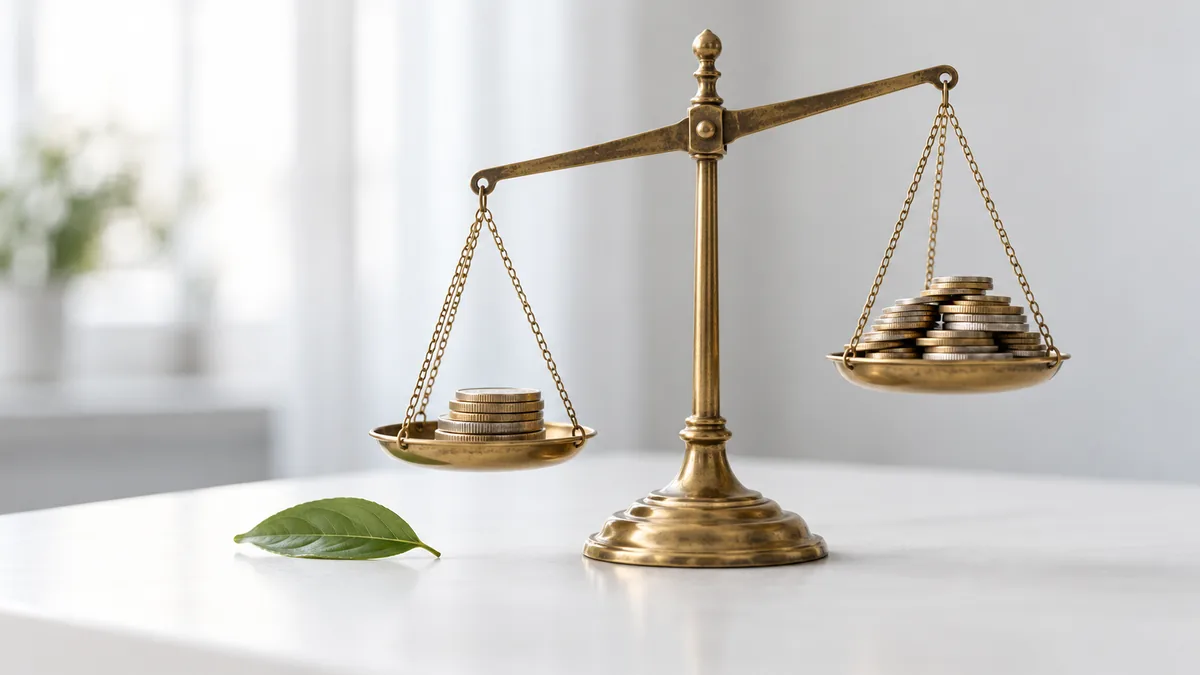
Imagine scales with one pan made of lead. Put €10 on both pans, and the scales still tip toward the loss. To balance them, you have to put more on the pan of the gain. This is an image, not a description of a mechanism in the head. But it conveys what we see in people’s decisions.
Scientists argue about why it works this way. What is clear is something else: the effect depends on conditions. According to the work of Ert and Erev, it is more noticeable when the safe option looks like something you already have, and when the stakes are large. With small stakes the tilt can be weak.
The reference point matters, too. A loss is always a loss compared with something: with what is in your wallet, with the price you paid, with your plan for the month. Move the reference point, and the same amount turns from a “loss” into a gain you did not get. That is why the same offer can seem both risky and attractive, depending on how it was described.
Where it gets in the way
Money. A person keeps money in an account that pays no interest for years, because any investment can go down. A possible drop feels scarier than the same rise feels good. Sometimes that is reasonable. But avoiding risk has a price, too. It just doesn’t show up on the statement.
Work and business. A team does not try a new way of working because “we could lose what is already running smoothly.” The possible gains seem foggy, and the possible losses concrete. In negotiations, your own concession is easily felt as a loss, and the other side’s concession as a modest gain. That makes it harder for both sides to budge.
Things. We ask more for our own things than we would pay for the same thing. In classic experiments, participants were handed ordinary mugs at random. Those who got a mug asked far more for it than those who did not get one were willing to pay. This is often explained by the same loss aversion: parting with a thing feels like a loss.
It is easy to confuse this with the sunk cost fallacy. There we cling to what has already been spent and will not come back. Here we avoid a future loss, even when the odds are in our favor.
How to decide more calmly
Loss aversion is one of the biases on the cognitive bias map, in the section on decisions and risk. In the same section is the anchoring effect: the first number we see influences what we consider a normal price.
Frequently asked questions
Is it true that a loss is always twice as strong as a gain?
No. “Twice” is a rough average across very different studies. In tasks involving risk, like the coin toss, the average came out lower, about 1.3. And individual people vary a lot: some are not afraid of losses at all, others demand a win several times larger.
Is this the same as negativity bias?
Close, but different. Negativity bias is about how bad things act more strongly on mood and attention. Loss aversion is about decisions: how much you have to promise a person for them to agree to take a risk.
Is loss aversion a bad thing?
Not always. Caution protects against losses you cannot afford. The trouble starts when it gets in the way where the loss is small and affordable and the benefit is real.
Is loss aversion the same as simply disliking risk?
Not exactly. In a game like Lisa’s coin toss the two get mixed together: part of what you ask for may come from a general dislike of risk, not only from the weight of the loss. Scientists separate the two in more careful ways than a game can.